Thorsten Rheinländer Memorial Colloquium
Monday, October 12, 2026, TU Wien, Vienna, Austria
General Information
The Thorsten Rheinländer Memorial Colloquium is dedicated to honoring the life, scientific achievements, and academic legacy of Professor Thorsten Rheinländer (1967-2025).
Colleagues, collaborators, former students, and friends will come together for a one-day scientific meeting featuring invited lectures reflecting the breadth of his research interests and his lasting impact on the field of mathematical finance.
Beyond celebrating scientific excellence, the symposium aims to commemorate Thorsten Rheinländer’s commitment to academic exchange, mentorship, and interdisciplinary collaboration.
Time:
Monday, October 12, 2026, 9:00-17:10
Location:
TU Wien (Technische Universität Wien)
"TU the Sky", 11th floor, building BA,
Getreidemarkt 9, 1060 Vienna/Wien, Austria (maps)
Registration:
Participation is free of charge.
For organisational purposes registration is required.
Organised by:
FAM @ TU Wien - Financial and Actuarial Mathematics Group of TU Wien
Organising Committee:
Julia Eisenberg (FAM @ TU Wien)
Stefan Gerhold (FAM @ TU Wien)
Peter Grandits (FAM @ TU Wien)
Friedrich Hubalek (FAM @ TU Wien)
Uwe Schmock (FAM @ TU Wien)
Sandra Trenovatz (FAM @ TU Wien)
Invited Speakers
Elisa Alòs (Pompeu Fabra University, Barcelona)
Paul Krühner (WU Vienna)
Jan Kallsen (Kiel University)
Natalie Packham (Berlin School of Economics and Law)
Dragana Radojicic (University of Belgrade)
Martin Schweizer (ETH Zurich)
Anke Wiese (Heriot-Watt University, Edinburgh)
Program
| 09:00 - 09:20 | Arrival & Coffee |
| 09:20 - 09:30 | Welcome Address |
| 09:30 - 10:15 | Anke Wiese (Heriot-Watt University, Edinburgh)
Squared Bessel Processes and Mean-Reverting Square-Root Processes: Direct Inversion and Calibration |
| 10:15 - 10:30 | Coffee Break |
| 10:30 - 11:15 | Natalie Packham (Berlin School of Economics and Law)
A Markov approach to credit rating migration conditional on economic states |
| 11:15 - 12:00 | Paul Krühner (WU Vienna)
Rheinländer's Brownian order book model |
| 12:00 - 13:30 | Lunch Break |
| 13:30 - 14:15 | Dragana Radojicic (University of Belgrade)
On the Conformity of Probability Distributions to Benford's Law: Statistical Properties and Financial Applications |
| 14:15 - 15:00 | Jan Kallsen (Kiel University)
t.b.a. |
| 15:00 - 15:30 | Coffee Break |
| 15:30 - 16:15 | Elisa Alòs (Pompeu Fabra University, Barcelona)
Option pricing via market completion and machine learning |
| 16:15 - 17:00 | Martin Schweizer (ETH Zurich)
Mean-variance hedging meets machine learning, for semimartingales |
| 17:00 - 17:10 | Closing Remarks |
Abstracts
Elisa Alòs (Pompeu Fabra University, Barcelona)
Option pricing via market completion and machine learning
A Margrabe or exchange option is an option to exchange one asset for another. In a general stochastic volatility framework, by taking the second asset as a numeraire, we derive pricing as well as approximate pricing formulae for Margrabe options. The correlated Stein & Stein and the 3/2 model are studied as particular examples. Moreover, we derive the general mean-variance optimal hedging strategy and show that it is a delta-hedge only in case of zero correlation between asset prices and volatility.
Joint work with Thorsten Rheinländer.
Jan Kallsen (Kiel University)
T.b.a.
t.b.a.
Paul Krühner (WU Vienna)
Rheinländer's Brownian order book model
Rheinländer has investigated a model driven by a simple invariant Brownian motion for the limit order book (LOB). The aim is to establish a mathematically transparent baseline model from which more sophisticated LOB models, such as those of Cont, Horst and others, may be viewed as natural extensions.
Interesting mathematical phenomena already appear in this base model. In this talk, we investigate this model and identify some principles that we hope are true in more general sense.
This work is based on previous work with Friedrich Hubalek and Thorsten Rheinländer.
Natalie Packham (Berlin School of Economics and Law)
A Markov approach to credit rating migration conditional on economic states
We develop a model for credit rating migration that accounts for the impact of economic state fluctuations on default probabilities. The joint process for the economic state and the rating is modelled as a time-homogeneous Markov chain. While the rating process itself possesses the Markov property only under restrictive conditions, methods from Markov theory can be used to derive the rating process's asymptotic behaviour. We use the mathematical framework to formalize and analyze different rat- ing philosophies, such as point-in-time (PIT) and through-the-cycle (TTC) ratings. Furthermore, we introduce stochastic orders on the bivariate process's transition matrix to establish a consistent notion of “better" and “worse" ratings. Finally, the construction of PIT and TTC ratings is illustrated on a Merton-type firm-value process.
Joint work with Michael Kalkbrener.
Dragana Radojicic (University of Belgrade)
On the Conformity of Probability Distributions to Benford's Law: Statistical Properties and Financial Applications
Benford's Law describes the non-uniform distribution of leading digits and has been observed in a wide range of naturally occurring and socio-economic datasets. The aim of this paper is to investigate the relationship between Benford's Law and probability distributions from both theoretical and empirical perspectives. We derive sufficient conditions under which selected continuous probability distributions conform to Benford's Law and examine the effect of their parameters on the degree of conformity. Particular attention is given to the Pareto and Weibull distributions, for which the theoretical results are complemented by simulation experiments assessing the variation in conformity across different parameter settings. The analysis is further extended to financial data to examine whether the theoretical properties of the underlying distributions are reflected in real-world observations. Using financial statement data from privately operated hospitals in Serbia, we assess the conformity of reported financial figures to Benford's Law and examine the role of distributional characteristics in explaining the observed leading-digit patterns.
Joint work with Jelena Stanojevic, Vesna Rajic, and Tatjana Rakonjac-Antic.
Martin Schweizer (ETH Zurich)
Mean-variance hedging meets machine learning, for semimartingales
One of the early areas of activities of Thorsten Rheinländer has been mean-variance hedging, especially in settings where the underlying price process is not a martingale. We revisit this problem and show how optimal strategies can be approximated with the help of neural networks. This is in the spirit of the seminal paper by Bühler, Gonon, Teichmann and Wood, but of course needs an extension to a continuous-time setting. Recent work by Arandjelovic has paved the way towards this, and we give an overview how the different strands of literature can be combined to provide results.
Anke Wiese (Heriot-Watt University, Edinburgh)
Squared Bessel Processes and Mean-Reverting Square-Root Processes: Direct Inversion and Calibration
The squared Bessel process plays a fundamental role in the modelling of economic and financial variables. An important example is the mean-reverting square-root process, which can be represented in terms of the squared Bessel process and is widely used in applications. Notable instances include the Cox-Ingersoll-Ross (CIR) interest-rate model and the Heston stochastic-volatility model.
In this talk, we derive new series expansions for approximating both the inverse distribution function of the squared Bessel process and its sensitivity with respect to its parameter, known as the dimension of the process. These results yield an efficient and highly accurate method for simultaneously simulating the squared Bessel process and its parameter sensitivity. We illustrate how this approach provides a flexible method for calibrating mean-reverting square-root models.
Further Abstracts t.b.a.
Registration
Participation is free of charge.
For organisational purposes registration is required.
We kindly encourage early registration to help us with the planning of the event.
Venue: TU the Sky
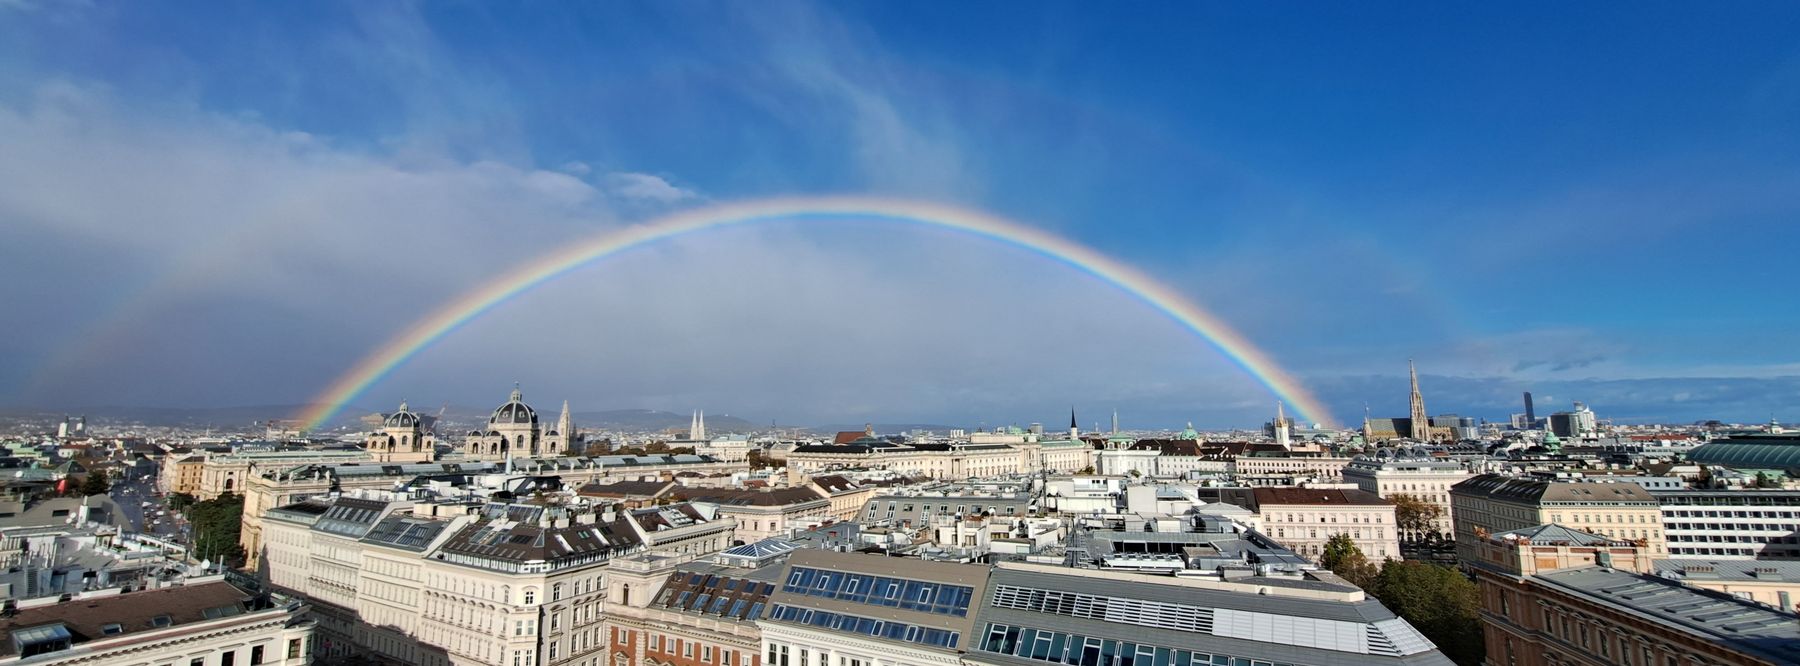
The venue is the representative rooftop louge "TU the Sky" located at the top (11th floor) of the high-rise building "BA" of TU Wien with a spectacular 360-degree view over Vienna - see the rainbow photo with view to the inner city of Vienna.
Address:
"TU the Sky", 11th floor, building BA of TU Wien
Getreidemarkt 9, 10460 Vienna/Wien, Austria (maps)
The building is located between Museumsquartier (metro line U2) and Karlsplatz (metro lines U1, U2, U4, nearest exit to the venue: "Secession").
Contact: Sandra Trenovatz <trmc2026@fam.tuwien.ac.at>